Twenty years ago Cisco was the name on the rack in almost every carrier network outside China. Today Huawei holds close to a third of the global telecom equipment market and Cisco holds about 4%. Cisco did not collapse along the way. It is having its best year ever. The two companies simply ended up running different businesses, and the split says a lot about how state money, engineering headcount and geopolitics shape who builds the world’s networks.
Where the Two Stand in Late 2026
Huawei reported 2025 revenue of CNY 880.9 billion, about $122 billion, up 2.2%. That is its second-best year after the 2020 peak, before US sanctions gutted its phone business. Net profit was CNY 68 billion. The ICT infrastructure segment, which holds the carrier gear, brought in CNY 375 billion and grew 2.6%. R&D took CNY 192.3 billion, or 21.8% of revenue.
Cisco reported fiscal Q1 2027 revenue of $18.5 billion on November 12, 2026, up 24% year over year. Product revenue grew 32%. The company raised its fiscal 2027 revenue guide to $74.8 to $75.8 billion and now expects $9 billion of AI infrastructure revenue from hyperscalers this year, more than double fiscal 2026. That money comes from data center switching, Silicon One chips and Acacia optics sold to cloud companies. Phone carriers are a small part of it.
| Huawei | Cisco | |
|---|---|---|
| Latest full-year revenue | CNY 880.9B (2025), about $122B | FY2027 guide $74.8B to $75.8B |
| Growth | 2.2% (2025) | 24% (Q1 FY2027) |
| Telecom equipment share, 1H 2025 | 31% | 4% |
| Main growth engine | Computing, digital power, cars | AI data center networking |
| Ownership | Private, employee-held | Public, NASDAQ: CSCO |
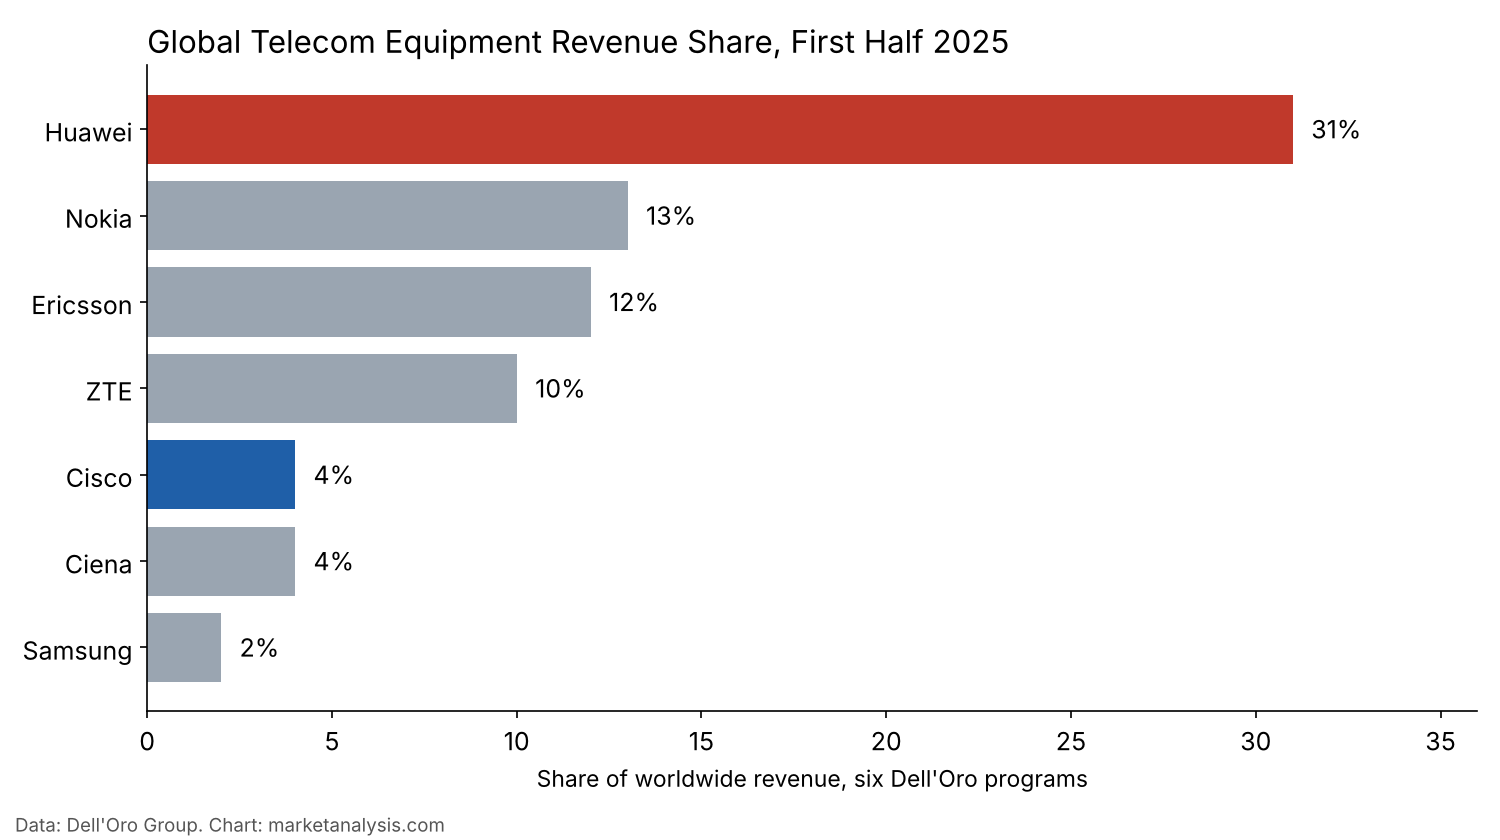
Dell’Oro’s figures for the first half of 2025 put Huawei at 31% of worldwide telecom equipment revenue, ahead of Nokia at 13%, Ericsson at 12% and ZTE at 10%. Cisco and Ciena had 4% each. Outside North America, Huawei’s share was 40%. Even excluding China it led with 21%.
Financing Won the Emerging Markets
The gap opened in the 2000s. China’s policy banks gave Huawei’s customers long, cheap vendor credit. A carrier in Nigeria, Indonesia or Peru short on capital could get radio, transport, core and the loan to pay for it in one deal. Huawei then earned service and upgrade revenue for years and fed it back into engineering. Cisco sold mostly to US and European carriers and enterprises. It was absent when mobile networks in Africa, Latin America and Southeast Asia were built out.
Standards and Headcount
Huawei put engineers into 3GPP and became one of the largest holders of declared 4G and 5G standard-essential patents. More than half its staff work in R&D. Its people spent years deploying gear in rural Africa, monsoon Asia and dense Chinese cities, and the products got tuned to messy field conditions. Contribution to standard to shipped product moved fast.
Cisco’s engineers went another way. Software, control planes, security and enterprise campus. That was a rational call. Carrier capex in the West was flat, hardware price wars were brutal and Wall Street paid for recurring software revenue. Cisco bought Splunk for $28 billion in 2024 and pushed into subscriptions. Margins held up. But it left Cisco out of the national infrastructure tenders where Huawei offered the whole stack from RAN to optical to power systems, often with diplomatic backing.
Sanctions Came Too Late to Reverse It
The US put Huawei on the Entity List in 2019. The UK, Sweden and others stripped it from 5G cores. Its handset business fell apart, and 2021 revenue dropped sharply. But the carrier installed base stayed. Networks built on Huawei gear keep buying Huawei upgrades, and the rip-and-replace programs in the US and Europe proved slow and costly. Sanctions also pushed Huawei to build its own chips, operating system and tools. Its Ascend AI chips are now a real factor in China, as covered in Huawei vs Nvidia in AI silicon.
Western carriers mostly moved to Nokia and Ericsson. Cisco never had much of the radio business to win back. That is why Nvidia chose Nokia for its $1 billion telecom bet, explained in Nvidia’s stake in Nokia.
Cisco Found a New Market Instead
Cisco’s comeback is in AI data centers. Hyperscalers need huge back-end fabrics to tie GPUs together and long-haul optics to link sites. Cisco booked $9.3 billion of hyperscale AI infrastructure orders in fiscal 2026, about 4.5 times the year before. Its networking revenue grew 43% in the latest quarter. Huawei is mostly locked out of that US cloud business, and Cisco is mostly locked out of carrier radio. Each company owns the lane the other cannot enter.
Huawei’s own growth now comes from outside the old carrier business too. Its connectivity revenue tracks a flat carrier capex cycle, while computing, digital power and car systems grew faster in 2025. The intelligent automotive unit rose 72% to CNY 45 billion.
What This Means for Investors and Buyers
- Telecom equipment is a slow market. Dell’Oro sees total 2025 revenue near $87 billion, up 4% after a 14% fall between 2022 and 2024. Growth in 2026 is coming from cloud providers buying optical and routing gear.
- Huawei’s share in carrier gear has stopped rising, but it holds. Its edge is entrenched installed base plus financing in countries Western vendors underserved.
- Cisco’s AI networking ramp is the story for CSCO stock. The risk is concentration in a few hyperscalers and the cyclical nature of capex.
- For security teams, the split matters too. Network vendor choice is now a geopolitical decision. See cybersecuritymarket.com for the security side of that trade-off.
The edge Cisco lost was in the carrier world, where state finance, field engineering and standards power mattered most. Huawei built networks and the political and financial ties around them. Cisco chose margins and the enterprise, and the AI build-out has paid that choice back. Both are giants. They just no longer compete for the same customers. For how the older wireless fights played out, read what happened to WiMAX, and for the wider technology picture visit technologies.org.
