• Skip to main content
  • Skip to secondary menu
  • Skip to footer

Market Analysis

Connecting the Dots, Quantifying Technology Trends & Measuring Disruption

  • AI Market Analyzer
  • Tech News
    • Project Dashboard
  • Domain Marketplace
  • Sponsored Post
  • About
  • Contact

IBM Will Never Be the Company It Used to Be

October 30, 2026

IBM will never again be the company that defined the direction of computing for much of the corporate world. That is my judgment about its place in the industry, rather than a prediction that its business will disappear. IBM can remain useful, profitable and deeply embedded in its customers’ operations. Recovering the authority of the old IBM would require something much harder: rebuilding a market in which one supplier could set the terms for so much of enterprise technology.

The photograph captures the company’s enduring presence rather well. A tall black IBM Security panel dominates the center of an exhibition stand, carrying a blue shield made of points of light above the red words “Open. Simple. Connect.” Broad white frames stretch out on either side under spotlights, while blue strips cross the dark industrial ceiling. Below, a bright red counter and white pedestal stools give the stand a clean, carefully organized appearance. The crowd makes it human: a woman stands on her phone in the middle, visitors talk in small groups, and dark jackets partly obscure the view from both sides. It is a substantial corporate presence, busy and professional. What the scene cannot establish is whether the company behind the sign still determines where the industry goes next.
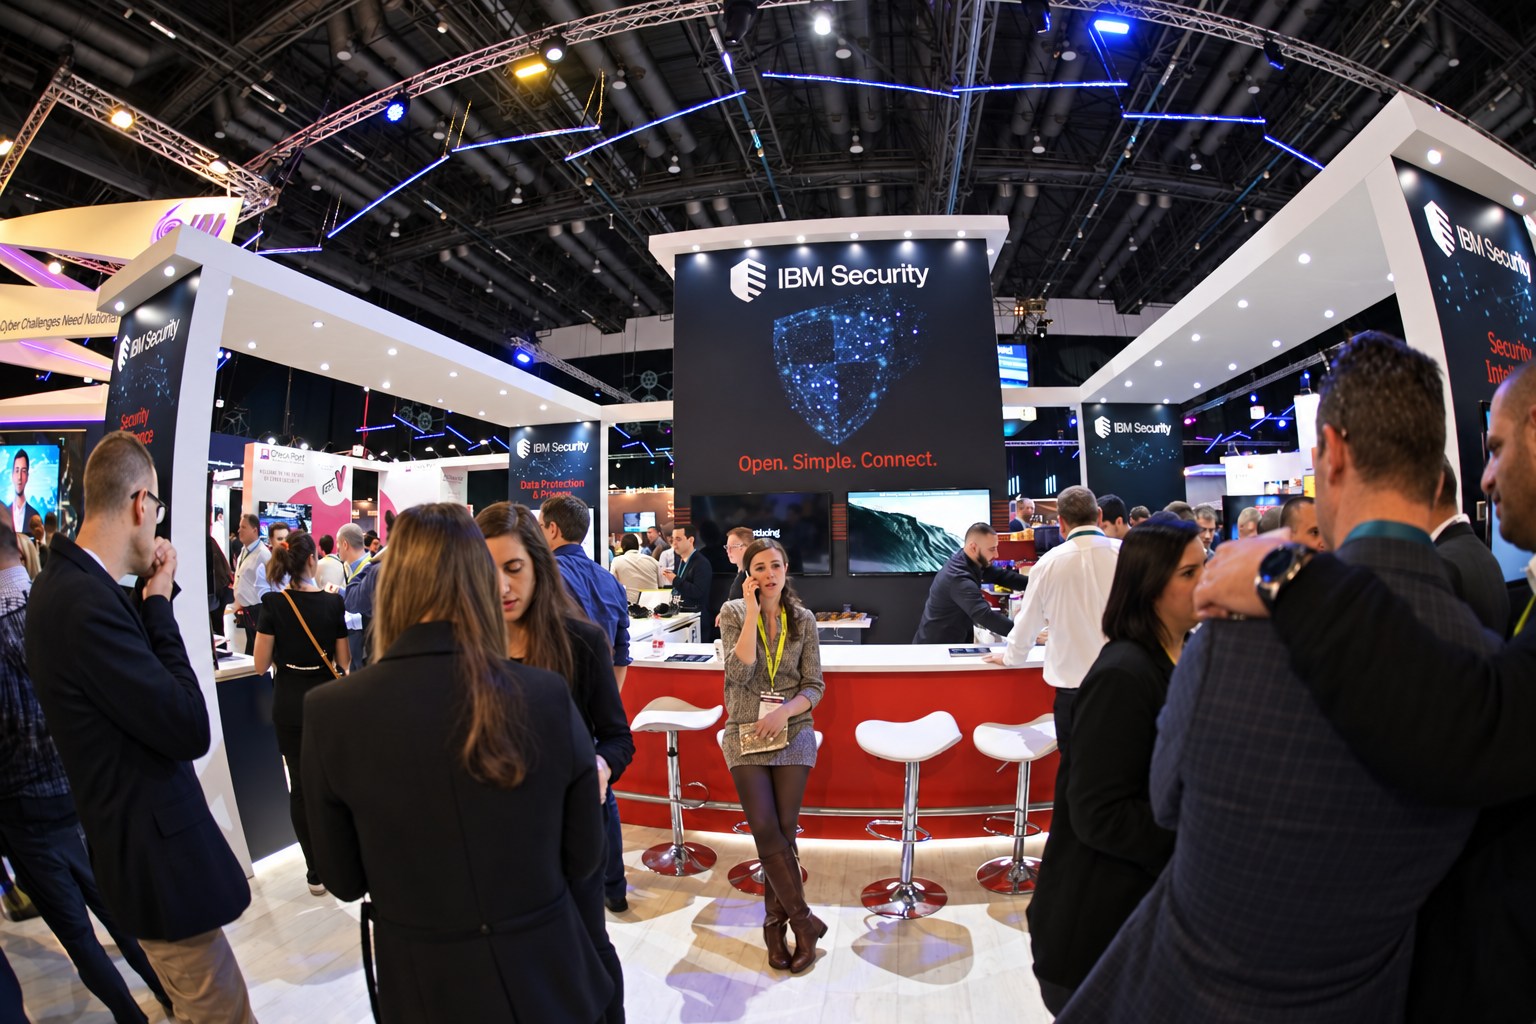
Visitors gather at a red counter beneath a large IBM Security panel, illuminated white booth frames and blue exhibition lights.
IBM Security exhibition booth.

The old IBM’s strength extended beyond selling individual machines. Its hardware, software and service relationships helped organize how large institutions bought and operated computing. System/360 embodied that power: a compatible family of machines made a customer’s investment in programs and skills useful across different levels of computing capacity. The commercial advantage came from the surrounding commitment as much as from the equipment itself. Buying into the system shaped subsequent decisions, sometimes for a very long time.

That history matters because today’s discussion too often treats reputation as though it were an asset that automatically renews. It does not. A familiar name can get a vendor into the meeting. It cannot guarantee ownership of the next important platform. IBM’s own personal computer helped expand a market whose economics increasingly favored suppliers of operating systems and processors. Creating a market and controlling its profits turned out to be different achievements. That lesson still has teeth.

The industry now gives customers more ways to assemble their technology from different suppliers. Every additional layer creates a separate contest over pricing and influence. A company can have a strong relationship with the chief information officer and still lose the next spending decision to a specialist elsewhere in the system. An incumbent’s importance to yesterday’s installation offers no automatic claim on tomorrow’s budget.

Artificial intelligence sharpens that problem. Helping a customer connect AI to existing business systems can be valuable work. Yet the supplier doing the integration does not automatically capture the economics of the chips, the hosting infrastructure or the application that the customer ultimately uses. My concern about IBM is that the language of transformation can blur this distinction. Being involved in an important technology transition is a much lower bar than controlling a scarce part of it.

The investment test should therefore be fairly blunt. Does a new offering win additional customers on its own merits, or mainly attach to relationships IBM already has? Does growth survive after acquisitions and currency effects are separated out? Can the company retain more of the revenue as cash without weakening the product or service that customers are buying? Those questions would help distinguish a stronger competitive position from a better presentation of the existing business. Announcements alone cannot answer them.

There is a serious argument in IBM’s favor, and dismissing it would make the criticism lazy. Large institutions have complicated systems, sensitive data and expensive consequences when things fail. A supplier that understands those constraints can earn durable revenue. Replacing an established platform can cost more than continuing to run it. Those economics can support a good business for a long time, even when the business rarely excites people outside its customer base.

But durability has limits as a growth thesis. Revenue protected by the difficulty of leaving is different from revenue won because new customers actively prefer the product. Both can produce cash. They deserve different expectations. An investor who confuses them can pay for an expanding platform and receive a carefully managed installed base instead. Whether IBM shares are attractive at any particular price requires a separate assessment of valuation and cash generation; this argument alone cannot settle that question.

What would change my mind is evidence that IBM had become a supplier customers increasingly chose for new projects even when they had little existing dependence on it. Sustained growth in that kind of demand would carry more weight than another promise to reinvent the company. Even then, success would look different from the old IBM’s dominance. The market has changed too much for a simple restoration.

The exhibition stand still fills the frame. The IBM name still draws people to the counter. My view is that the company can build a worthwhile future, but the industry it once commanded is gone. Its next chapter has to earn its own value.

Filed Under: Technology and Software Tagged With: enterprise software, generative AI, stock market

Footer

Recent Posts

  • Anthropic Shares Rise 21% on IPO Debut, but the Wider AI Market Sends a Different Signal
  • Quad9 France Exit Turns DNS Blocking Into an Infrastructure Market Risk
  • Robot Market Fight Heats Up as US Orders Jump 25% and Chinese Humanoid Makers Lose CES Visas
  • Anthropic (ANT) Prices at 83 Dollars and Wall Street Wraps It in 2x ETFs and CFDs Within Days as Cantor Explains Its Nvidia Hedges
  • Hormuz Risk Gauge Falls to 63.8 High as the Dubai Premium Vanishes While Tanker Attacks Keep Coming
  • China Turns AI Model Distillation Into Industrial Policy and Weakens the Reach of US Chip Controls
  • AI-Found Software Flaws and the Rush to Patch Them Are Now a Market Risk After a Week of US Outages
  • Ohio Voters Put $17 Billion of Amazon Data Center Spending at Risk as Local Bans Spread
  • US Remote Access Chip Rule and FCC Optics Ban Squeeze Southeast Asia Data Centers and Nvidia China Exposure
  • Microsoft Puts Word, Excel and PowerPoint Inside Copilot and Turns Office Into an AI Front Door

RSS feed: Market Research Media Market Research Media

  • Four Vendor Surveys on Missed AI Returns Each Find the Problem Their Sponsor Sells a Fix For
  • Wasabi Study Puts Unplanned Infrastructure Spending at $63.4 Billion, With Germany Overspending by 7.1 Billion Euros
  • CSC Survey Finds 88% of Private Capital GPs Spend Up to Half Their Finance Time Checking Administrator Work
  • Lenovo Survey Finds 80% of IT Leaders Tie AI Success to the Digital Workplace and Only 10% Have Redesigned It
  • Claude and ChatGPT Integrations Killed the Headless CMS Market
  • Survey Margin of Error Explained, What Plus or Minus 3 Points Covers and What It Leaves Out
  • Morgan Stanley Pulse Survey Finds Bearish Investor Sentiment Rising to 42 Percent as Inflation Fears Grow
  • A Stronger Week Across the Network, October 4–10, 2026
  • The Tariff Map Is Becoming an Industrial Policy Map—and the U.S. Economy Is Paying the Price
  • PC Shipments Fall 22.4% as Higher Component Costs Price Buyers Out

Media Partners

  • Analysis
  • Technology Conferences
  • OSINT
  • Defense Market
  • Cybersecurity Market
  • Event Calendar
  • Calendarial
  • Opinion
  • 3V
  • Media Presser
  • Exclusive Domains

Copyright © 2026 MarketAnalysis.com | Terms of Service | Privacy Policy | Supplier Disclaimer | The Website Coded and Designed by SoftDev Studio

Media Partners: Technologies | Photography | Referently

We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
Do not sell my personal information.
Cookie SettingsAccept
Manage consent

Privacy Overview

This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary
Always Enabled
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
CookieDurationDescription
cookielawinfo-checkbox-analytics11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional11 monthsThe cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy11 monthsThe cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytics
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Others
Other uncategorized cookies are those that are being analyzed and have not been classified into a category as yet.
SAVE & ACCEPT